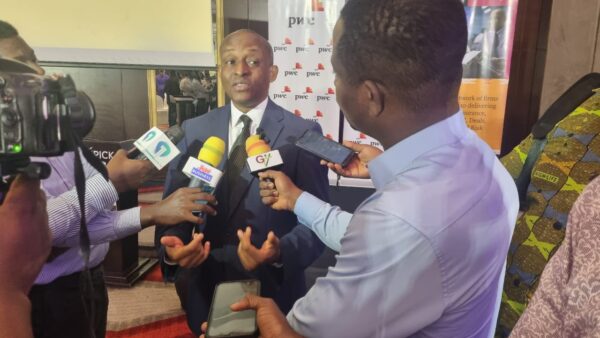
Vish Ashiagbor speaking to the media
The Senior Partner at PricewaterhouseCoopers (PwC) Ghana, Vish Ashiagbor has advised banks in Ghana to invest more in improving their operational index in a bid to enhance their effectiveness.
His comment is in reference to key findings from the maiden edition of the Ghana Banking Sentiment Index (GBSI).
The Index reveals that in terms of operational net sentiment, Ghanaian banks recorded a score of -23.5%, which was better than UAE’s, UK’s, Saudi Arabia’s, and Kenya’s respective scores, but worse than South Africa’s 2023 score of 9.7%
Ghanaian banks however scored 21.8% in terms of reputational net sentiment when it comes to banks in the country.
This is better than scores obtained by the banking industries in the UK (2023), and the UAE and Saudi Arabia (2024). It was, however, worse than the South African and Kenyan markets.
Speaking to Journalists on the sidelines of the presentation of the key findings at PwC’s Banking CX Breakfast Forum on Tuesday (27 August) in Accra, Ashiagbor said Banks must do more to enhance customer experience
“I think that banks need to look at their stakeholders, understand what exactly they want and adjust their ways to suit them, it is not as easy as it sounds because the stakeholder environment is huge and I think that is where the challenge is.”
“So some of the things we are speaking about such as speed , predictability, knowledge of employees,..so Banks need to be clear of what the changing needs of their customers so that they can change their internal processes are and be able to adjust, because what,” Ashiagbor said.
About Ghana Banking Sentiment Index (GBSI)
Co-developed by PwC and DataEQ, the Ghana Banking Sentiment Index (GBSI) provides a gauge for the overall customer sentiment towards the banking industry. The production of the index follows a robust methodology that entails collecting and rigorously analysing social media conversations relating the good and poor experiences that social media-active customers have with their banks.
The maiden edition of the GBSI was produced from analysing almost 62,450 conversations on Facebook and X (formerly Twitter), with these conversations having taken place from 1 April 2023 to 31 March 2024. 13 of the 23 banks operating in Ghana during this period have been covered in the very first edition of the GBSI. Exclusions from the index are due to insufficient mentions of a bank in the sampled conversations on these two social media platforms, which are, by far, the most popular among customers.
The two firms found that 77% of the social media conversations tracked are reputational in form, mostly driven by the marketing departments of the banks covered and influencers associating with the banks’ brands. The remaining 23% of the social media conversations are classified as operational, mostly spontaneous praise and complaints by customers relating their experience with their banks.
Ghana Banking Sentiment Index (GBSI)
Co-developed by PwC and DataEQ, the Ghana Banking Sentiment Index (GBSI) provides a gauge for the overall customer sentiment towards the banking industry. The production of the index follows a robust methodology that entails collecting and rigorously analysing social media conversations relating the good and poor experiences that social media-active customers have with their banks.
The maiden edition of the GBSI was produced from analysing almost 62,450 conversations on Facebook and X (formerly Twitter), with these conversations having taken place from 1 April 2023 to 31 March 2024. 13 of the 23 banks operating in Ghana during this period have been covered in the very first edition of the GBSI. Exclusions from the index are due to insufficient mentions of a bank in the sampled conversations on these two social media platforms, which are, by far, the most popular among customers.
The two firms found that 77% of the social media conversations tracked are reputational in form, mostly driven by the marketing departments of the banks covered and influencers associating with the banks’ brands. The remaining 23% of the social media conversations are classified as operational, mostly spontaneous praise and complaints by customers relating their experience with their banks.
The GBSI debuted with the following results:
- A Public Net Sentiment score of 10%, which is better than the UK’s -25.6% (2023), the UAE’s -13% (2024), and Saudi Arabia’s 0.1% (2024), but worse than Kenya’s 16.3% (2024) and South Africa’s 23.5% (2023)
- An Operational Net Sentiment score of -23.5%, which was better than UAE’s, UK’s, Saudi Arabia’s, and Kenya’s respective scores, but worse than South Africa’s 2023 score of 9.7%
- A Reputational Net Sentiment score of 21.8%. This is better than scores obtained by the banking industries in the UK (2023), and the UAE and Saudi Arabia (2024). It was, however, worse than the South African and Kenyan markets.
Details presented along with the summary results of the index show the experiences the industry and individual banks covered are giving customers in the areas of products, customer service, digital interactions, account administration, transactions and pricing, and physical infrastructure.
PwC and DataEQ noted that the five areas of analysis that attracted the most negative sentiments from customers were as follows: account administration (-93.2%); customer service (-84.2%); transactions (-82.5%); digital experiences (-75.1%); and physical facilities (-63.8%).
- Account administration and customer service:customers biggest pain was around billing and payments, turnaround times, and account irregularities, with the underpinning causes attributed to poor or “behind-the-curve” technology, as well as a reluctance by banks to resolve experience-related challenges quickly.
- Digital experiences:out of eight different bank channels mentioned in social media conversations, mobile apps accounted for almost a third of all conversations. The sentiment expressed by customers about mobile apps was the most positive among all the channels, though it was -50.4%. ATMs accounted for 7% of volume of channel mentions and had the worst sentiment score, i.e. -84.4%, while branches (accounting for 23% of mentions by volume) scored a net sentiment of -58.7%. Again, customers’ dissatisfaction with the experiences provided by their banks attributed it to malfunctioning apps and ATMs (i.e., system availability, challenged logins and authentication, interrupted transactions, failed reversals, etc.), long waiting times at branches and unhelpful bank staff.
Reporting by Fred Dzakpata in Accra